Published · Last updated
For owners and sellers
What to document before you sell industrial land in 2026
Before selling industrial land in 2026, document four things: distance to the nearest substation and its capacity, the voltage of the nearest transmission service, a utility load-study response with a queue position, and the exact procedural history of every entitlement approval. Those four items separate a warehouse price from a powered-land price, and powered land averaged $584,000 per megawatt in primary US markets in 2026 year to date.
Key takeaways
- Substation distance is priced. Inside half a mile: roughly 2x the per-acre price of two-to-five-mile sites (Altus Group, August 2026).
- Voltage is priced. 230kV or 500kV service: roughly 2.4x the price of 138kV-and-below service.
- Size is priced inversely. Sub-25-acre infill averaged $3.3M/acre; 1,000-plus-acre greenfield averaged $28,000/acre.
- The ceiling is real. Starwood Capital paid Fairfax County $166.8M for 42 acres at 3721 Stonecroft Boulevard in Chantilly, Virginia on 24 March 2026 — roughly $4.0M per acre.
- Procedure kills deals. The 2,100-acre, 22M sf Virginia Digital Gateway died because hearing notices were not six days apart. Buyers now diligence the notice history.
A quarterly brief on powered land, port capacity and air-cargo gateways, plus the Powered Land and Gateway Pricing Benchmarks data file.
- Dollar per megawatt and dollar per acre benchmarks by market, with the substation-distance and voltage premiums applied
- Every committed United States port capacity opening from 2026 through 2035, with cost, TEU and date
- Airport-adjacent rent premiums by gateway, and the constraint map that drives them
- The named project pipeline: site, megawatts, developer, power source, status
- Sources and periods for every cell. Nothing unattributed.
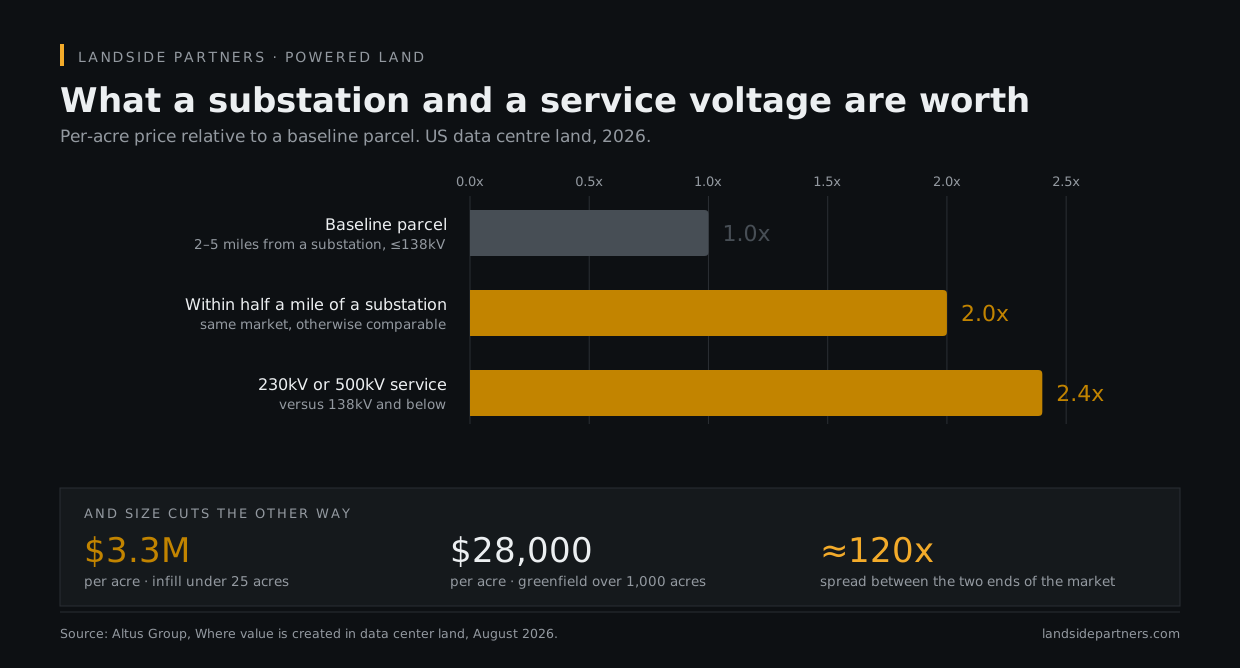
| Attribute | Multiple of baseline |
|---|---|
| 2–5 miles from a substation, ≤138kV | 1.0x |
| Within half a mile of a substation | 2.0x |
| 230kV or 500kV service | 2.4x |
The document pack that earns a premium
A buyer's first question is never what you want for the land. It is what you can prove.
Power
- Utility load-study request and the utility's written response
- Interconnection queue position, cluster, and current screening status
- One-line diagram of the nearest substation with nameplate and available capacity
- Nearest transmission voltage and the distance to the tap point
- Interconnection cost estimate and who bears network upgrades
- For ERCOT: SB6 readiness — site control, financing evidence, timeline, and the $50,000 per MW security posture
- Gas: nearest transmission pipeline, diameter, pressure, and a transporter willingness letter if behind-the-meter generation is contemplated
Water
- Source, allocation and permitted withdrawal
- Discharge capacity and permit path. Thermal discharge is the friction point, not intake.
Land and entitlement
- Current zoning and by-right uses, with the ordinance text
- Every approval's procedural record: notice dates, publication proofs, hearing minutes, appeal windows
- ALTA survey, Phase I and where indicated Phase II, wetlands delineation, floodplain, geotech
- Title with a clean read on easements. Transmission and pipeline easements can be an asset here, not a defect.
Access
- Rail frontage and the serving carrier's willingness to serve
- Highway access and any required turn-lane or signal improvements
- Distance and drayage cycle to the relevant port gate or airport cargo gate
- Fiber routes, long-haul carriers present, and distance to the nearest subsea cable landing station
Why timing favours starting early
The Altus finding — that 30 to 40 months of utility coordination, entitlement and tenant negotiation typically precede the moment a transaction becomes publicly visible — is the argument for starting the document pack before you want to sell, not after you have an offer. Owners who begin power documentation two years ahead of a sale are the ones who get a bid from a pool they did not know existed.
Where the buyers are right now
- Data center developers and their capital. CBRE's April 2026 investor survey found 55% of respondents planning to increase buying activity by more than 10%, with 78% naming Dallas-Fort Worth and 72% Northern Virginia as the most attractive markets, and 44% targeting opportunistic new development.
- Hyperscalers buying directly. Microsoft's FY2026 capex came in at $115.9B. Alphabet guided calendar 2026 to $195 to $205B. Meta guided to $130 to $145B. Amazon spent $98.4B in the first half of 2026 alone, up 72% year on year. Oracle spent $55.7B in FY2026 and guided FY2027 to $70B net.
- Crypto-to-AI converters with power but not enough land. TeraWulf's $9.5B Fluidstack and Google joint venture, Cipher Mining's $5.5B fifteen-year AWS lease, Applied Digital's $5B fifteen-year lease, Hut 8's $7B fifteen-year lease, and IREN's $1.9B Microsoft prepayment.
- Industrial outdoor storage aggregators. Alterra IOS has acquired more than 470 sites and raised a $100M BMO facility in January 2026, a $244M Blackstone Real Estate Debt Strategies loan in June 2026, and a $400M Truist and KeyBank refinancing in July 2026. Zenith IOS holds roughly 100 properties at about $1.2B.
- Logistics landlords crossing into data centers. GLP carries a roughly 2,500 MW pipeline. ESR holds 260 MW owned or in development against a 1,200-plus MW combined pipeline. Prologis partners with Skybox on greenfield and warehouse conversions.
Get a Landside Read on your parcel.
No fee. One parcel. One page. Usually back within five business days.
A quarterly brief on powered land, port capacity and air-cargo gateways, plus the Powered Land and Gateway Pricing Benchmarks data file.
- Dollar per megawatt and dollar per acre benchmarks by market, with the substation-distance and voltage premiums applied
- Every committed United States port capacity opening from 2026 through 2035, with cost, TEU and date
- Airport-adjacent rent premiums by gateway, and the constraint map that drives them
- The named project pipeline: site, megawatts, developer, power source, status
- Sources and periods for every cell. Nothing unattributed.
This research was produced by Landside Partners, a commercial real estate research and advisory firm working with owners of industrial land across North America on data center, seaport and air-cargo demand. To have a specific parcel assessed, contact Brad Cohen at Landside Partners.
Related research
- Data Centers — Pillar: US data center demand, vacancy and the pipeline that has to find land, Q2 2026.
- Ports — Pillar: committed, funded and dated US gateway capacity and near-port industrial pricing, Q2 2026.
- Air Cargo — Pillar: airport-adjacent industrial metrics and cargo gateway rent premiums, Q2 2026.
- Markets — Index of the twelve covered metros with each market's headline figure, Q2 2026.
- Research — Research hub: powered land, floating siting, ports and air cargo, published free in full.
Published · Last updated